How the 2027 Social Security COLA May Affect Your Budget
Read more
Why Long-Term Care Planning Supports a More Secure Future
Long-term care planning is an essential part of preparing for the future, especially as retirement approaches. Many people focus on saving, investing, and building financial stability, but they...
Read more
Medicare Annual Enrollment: Your Top 5 FAQs Explained
The Medicare Annual Enrollment Period (AEP), running every year from October 15 to December 7, is your once-a-year window to update your Medicare coverage. Since this timeframe is limited, it’s...
Read more
When To Reevaluate Life Insurance As Your Income Grows
Life insurance plays a crucial role in protecting the people and goals that matter most. But as income rises and responsibilities shift, coverage that once seemed sufficient may no longer match...
Read more
Why Your Medicare ANOC Deserves a Careful Review This Year
The Annual Notice of Change (ANOC) is one of the most important documents Medicare beneficiaries receive each year, yet it is often overlooked. This notice outlines updates to Medicare Advantage...
Read more
Understanding Return of Premium Life Insurance Riders
Read more
Medicare Guidance for Confident Summer Travel
Summer is a favorite time for road trips, family visits, and long-awaited vacations. But before you pack your bags, it’s important to understand how Medicare works once you’re away from home. Many...
Read more
UV Safety Awareness Month - July - Skin Cancer Prevention
Sun exposure affects your skin far more often than you might realize. Even brief moments outside—or time spent near windows—allow UV rays to reach your skin, adding up quietly over the years. UV...
Read more
Oral Health Month - June - Dental Insurance Myths Debunked
Dental insurance is widely used but often misunderstood, leaving many people unsure about how their coverage works or why certain services cost more than expected. When misconceptions go unchecked,...
Read more
Medicare and Eye Care: What’s Covered and What Isn’t
June 6th, recognized as Visually Impaired People Day, serves as a timely reminder of the vital role eye health plays in everyday life. As individuals age, routine and specialized vision care often...
Read more
Why Life Insurance Can Be a Meaningful Graduation Gift
Graduation brings a mix of celebration, hope, and new beginnings. It is also a moment when families look for meaningful ways to honor the transition from one chapter to the next. While cash,...
Read more
Medicare Advantage Trial Right, Explained
The Medicare Advantage trial right gives new enrollees a unique safety net during their first year of Medicare Advantage coverage. This one-time protection allows you to explore a Medicare...
Read more
Refresh Your Life Insurance Beneficiaries This Spring
Spring naturally inspires us to reset, reorganize, and clear out the clutter that’s built up over the year. As you’re tackling closets, cleaning out drawers, or tending to long-overdue home...
Read more

Life Insurance vs. AD&D: What You Need to Know
Read more
Heart Health Myths Debunked: What Really Matters This American Heart Month
February marks American Heart Month, making it the perfect time to turn our attention to the organ that keeps everything in motion — the heart. Even though heart disease continues to be the top...
Read more
Essential Heart Health Tips and Medicare Insights
February marks American Heart Month, a time to not only don red attire but also adopt meaningful measures for better heart health. Heart disease stands as the leading cause of death globally,...
Read more
Understanding Your Medicare Advantage Trial Right
Navigating the world of Medicare options can be daunting. With a myriad of choices and regulations, it's easy to second-guess your plan selection. The Medicare Advantage trial right is a crucial...
Read more
Maximize Your Benefits Before 2026: A Year-End Plan
The end of the year is fast approaching, and it's easy to get caught up in the holiday hustle. During this busy time, it’s not uncommon to overlook vital health and financial benefits that could...
Read more
ACA Open Enrollment: Navigating 5 Key FAQs
Read more
End-of-Year Life Check: Is Your Coverage Still Right?
As the year draws to a close, it’s a natural time for reflection. The holiday season, combined with the open enrollment period, creates the perfect backdrop for reevaluating your life insurance...
Read more
End-of-Year Reflection: Is Your Insurance Keeping Pace?
Rethinking Life Coverage as the Year EndsAs the year draws to a close, many of us find ourselves reflecting on the past months—a period marked by both joys and challenges. The holiday season,...
Read more
ACA Open Enrollment: Key Dates You Shouldn't Miss
The Importance of Health CoverageHealth insurance is a vital necessity to ensure your well-being and financial stability. The Open Enrollment Period for the Affordable Care Act (ACA) offers a...
Read more
Understanding OBBBA: Key Changes for Seniors
The Complex World of Legislative ChangesLegislative changes can be overwhelming, especially for our older adults, when they touch on critical areas such as finances, healthcare, or long-term care...
Read more
Plan Now to Use Your Benefits Before You Lose Them!
As the year rapidly draws to a close, it's astonishing how swiftly the final months seem to sprint by. Amidst the bustling holiday preparations, it's easy to overlook some crucial health and...
Read more
Celebrate National Eye Exam Month: Prioritize Your Vision
August is National Eye Exam Month!August is recognized as National Eye Exam Month, marking a perfect opportunity to focus on your eye health. This month serves to remind us that getting an eye exam...
Read more

Life Insurance: Beyond the Basics - Hidden Advantages
Read more
Medicare's Skin Cancer Coverage: What You Need to Know
Summer's Sun: A Call for Skin AwarenessAs the sun-drenched days of summer approach, those delightful rays also bring the potential for increased sun exposure. For many, especially those over 65,...
Read more

Common Scams to Watch Out For on Senior Fraud Awareness Day
On May 15, we observe National Senior Fraud Awareness Day—a crucial reminder to stay vigilant against scams targeting older adults. If you have an elderly loved one or are simply concerned about...
Read more
Choosing Between Life and Accidental Death Insurance
Understanding the Essential Role of InsuranceFinancial planning is a cornerstone of ensuring that your loved ones are protected in the unfortunate event of your passing. Navigating the complex...
Read more
Medicare Supplement Plan G vs. Plan N: Which is Right for You?
When it comes to Medicare Supplement plans, Plan G and Plan N are two of the most popular choices for seniors looking to reduce out-of-pocket healthcare costs. But which one is the best fit for you...
Read more
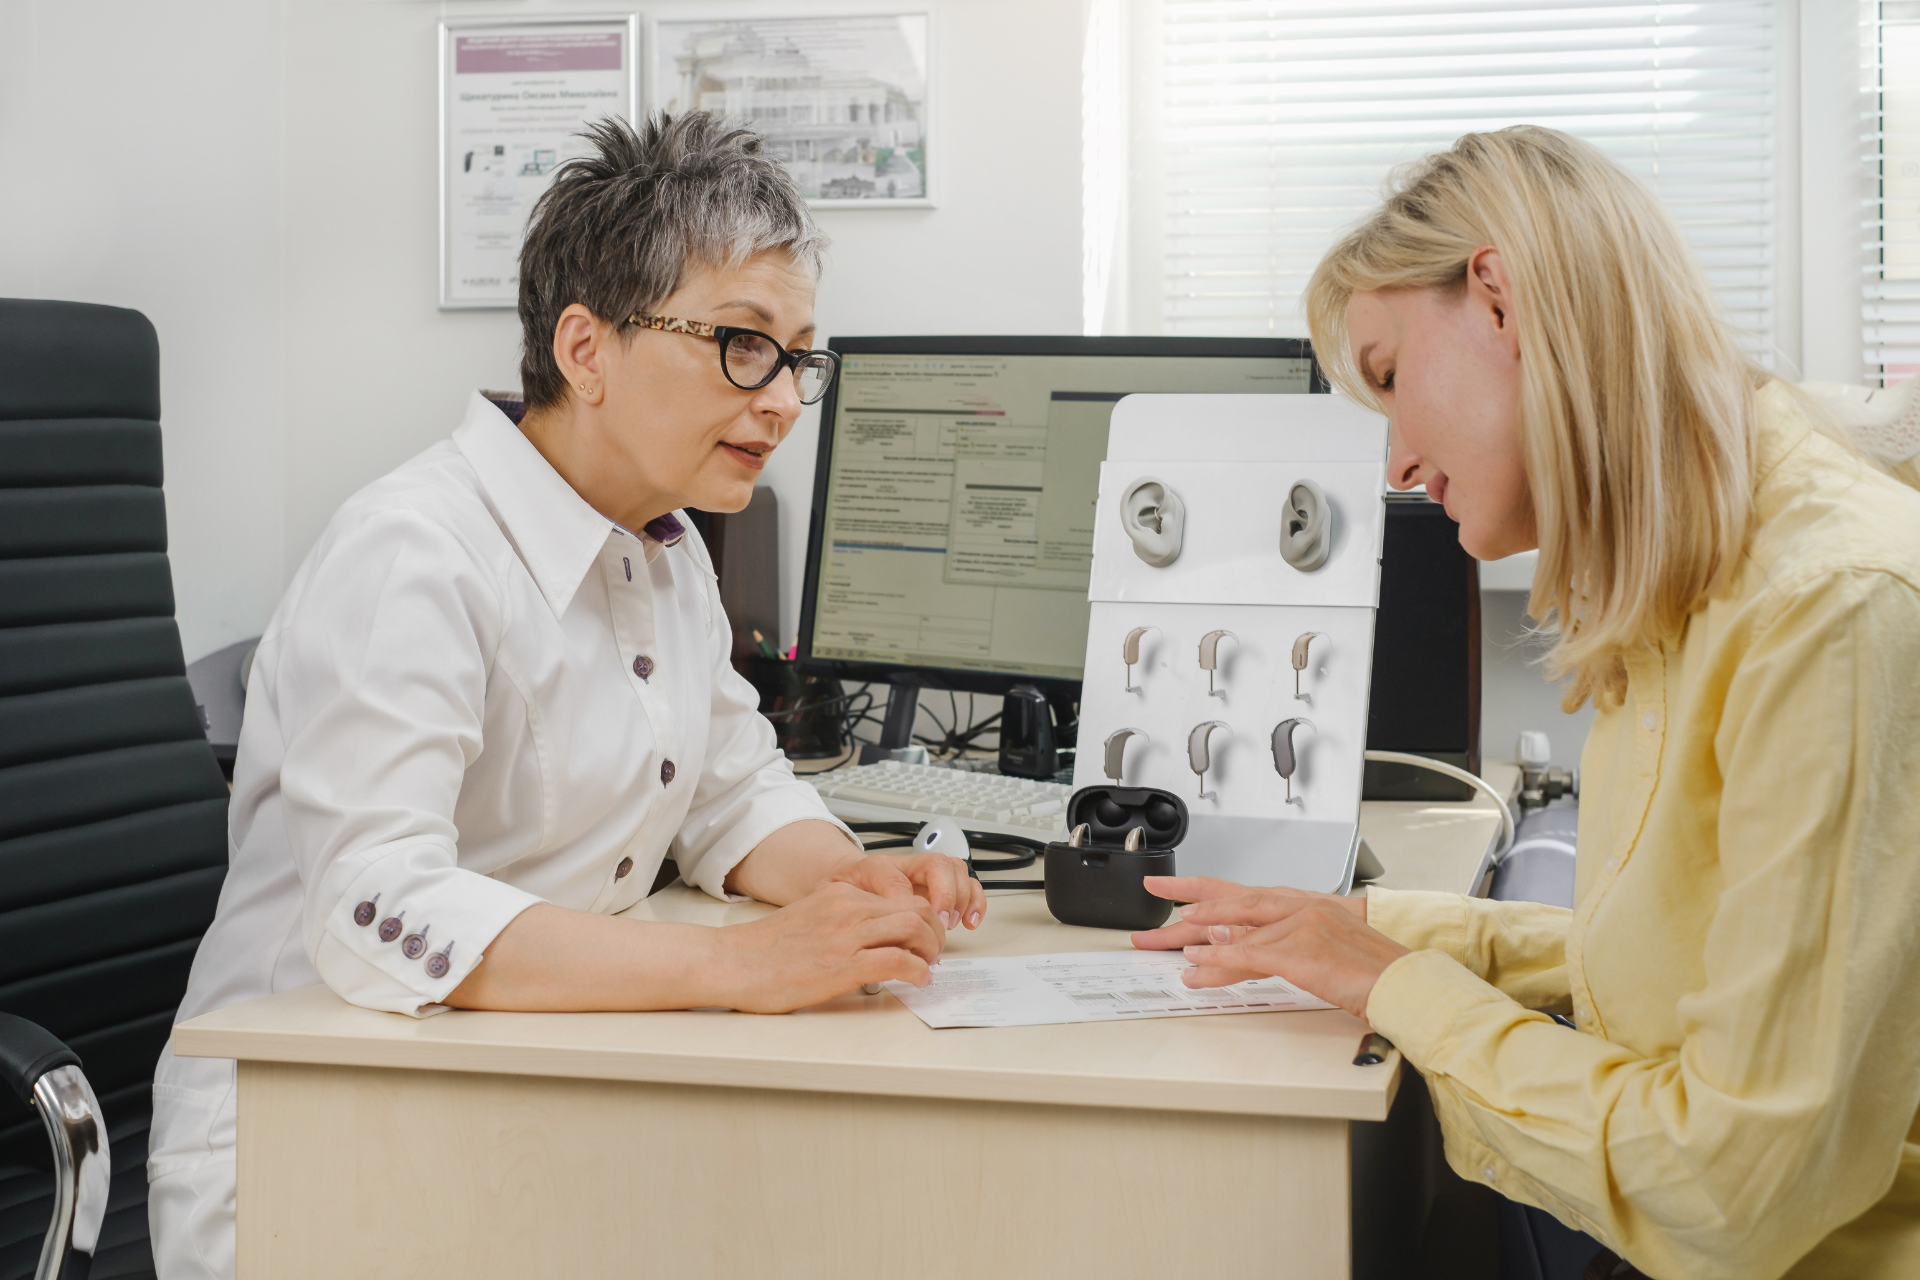
What is the Best Hearing Insurance for Seniors in Texas?
As we age, hearing loss becomes a common concern, and the cost of hearing aids and treatments can add up quickly. Unfortunately, Original Medicare does not cover hearing aids or routine hearing...
Read more
The Importance of Life Insurance for Families in Burleson, TX
Life is full of uncertainties, and for families in Burleson, TX, ensuring financial security for loved ones is a top priority. Life insurance provides peace of mind by offering financial protection...
Read more
Your Guide to Choosing the Best Medicare Plan in Burleson, TX
As you approach Medicare eligibility, selecting the right plan can feel overwhelming. With multiple options like Medicare Advantage, Medicare Supplement, and Part D prescription plans, it’s...
Read more

Navigating the Medicare Reimbursement Maze
Read moreView more